For the better part of three years, the hottest seat in London's multi-manager world was a European rates book: lever up French OATs in repo, clip the carry, collect the seven-figure payout. This month, the French bond market sent the bill.
According to a must-read report from eFinancialCareers' Sarah Butcher, London's macro hedge funds are quietly emptying out their EGB desks. Funds aren't talking about performance, but headhunters and bank traders who have been keeping score say the count of ejected European rates PMs and traders has climbed from the mid-70s a few weeks ago to close to 100 people. One senior trader at a liquidity provider summed it up in four words: "Everyone has blown up... they are all out"
In other words, the most crowded trade in European fixed income just found out what happens when the collateral is the problem.
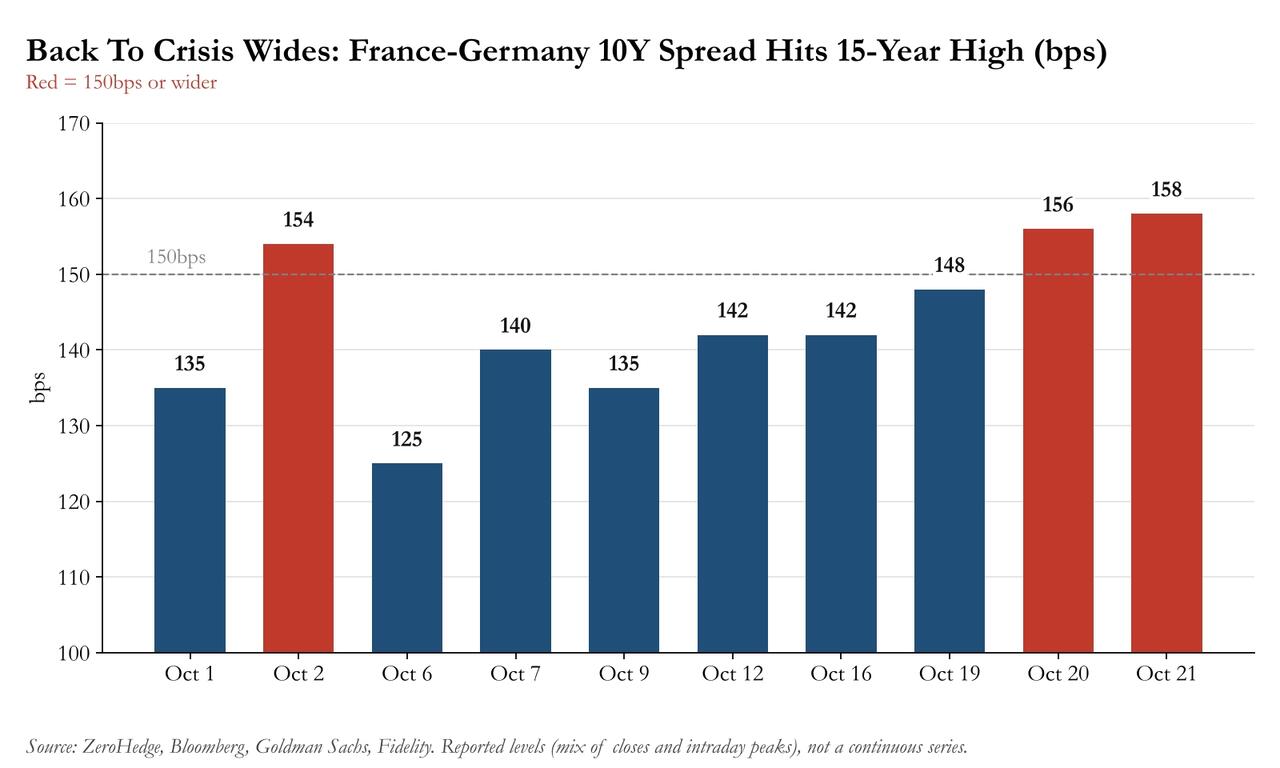
And the bleeding hasn't stopped. This morning Bloomberg flashed that the French bond risk gauge is nearing 160bps, a fresh 15-year high, while French 10Y yields hit 5% for the first time since July 2002.
Below we walk through what blew up, why it blew up (twice), what Goldman, Morgan Stanley and the rest of the Street make of it, and why the market's attention is already drifting to the next domino: Italy.
The Trade: Borrow Against France, Pocket The Difference
The mechanics were simple eno