Here is a question that should be harder to answer than it is: China still controls the rare earth spigot, the latest Trump-Xi summit did nothing to loosen its grip, Japan is about to run out of yttrium, Washington has put a $110/kg floor under NdPr, and Western buyers are paying anywhere from 5x to 346x the Chinese price for heavy rare earths.
So why are rare earth stocks down on the year?
That is the question Canaccord's critical minerals team led by Reg Spencer asks in an overnight note titled "Rare Earths: Equity disconnect from strong market fundamentals", and the answer is blunt:
Given our favourable SxD outlook, floor pricing, recent pricing stability (NdPr), and Western pricing premiums (particularly for heavies), we think recent equity performance has been driven more so by global macro factors and highlights a disconnection from rare earth market fundamentals.
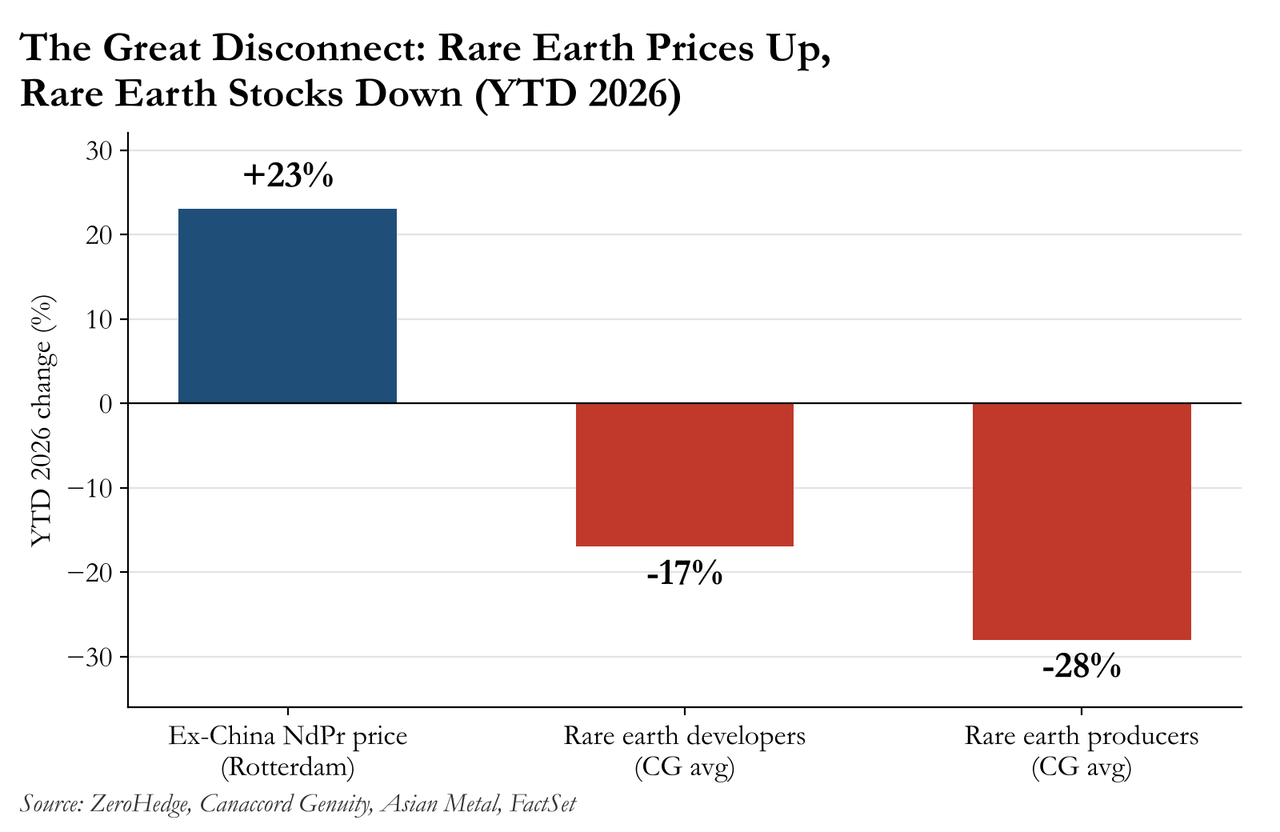
In other words, the commodity is acting like a strategic asset and the stocks are trading like a risk-off casualty. The numbers are stark: year to date, the ex-China NdPr price is up 23%, while Canaccord's rare earth developers are down 17% on average and its producers are down 28%.
We have been tracking the rare earth theme since long before China started rationing exports to the West in late 2024, and back in July 2025 we laid out READ MORE AT SOURCE »
« Back to The Culture War