RTX Corp., formerly Raytheon Technologies, raised its full-year outlook for a third straight quarter as the Western rearmament supercycle gathers momentum.
Wall Street welcomed the earnings update: RBC Capital Markets called the results "strong," Goldman Sachs highlighted a "solid quarter" with higher guidance, and UBS pointed to "accelerating defense growth."
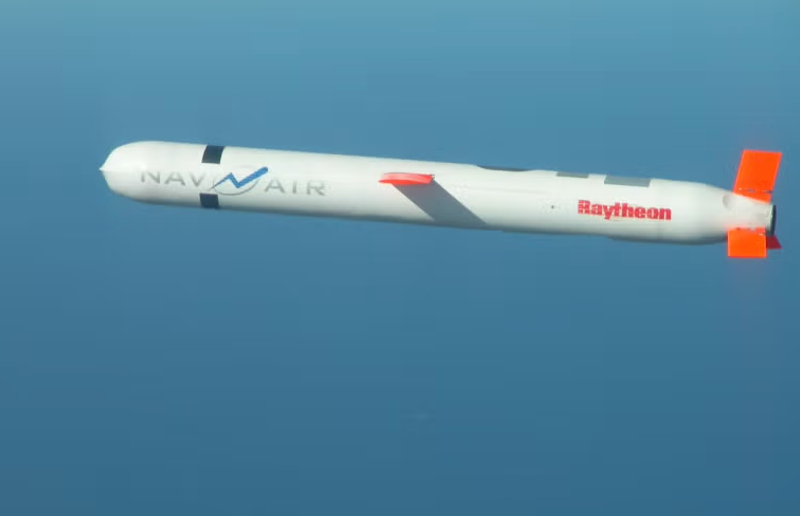
The Tomahawk cruise missile maker reported third-quarter earnings earlier and now expects 2026 adjusted earnings of $7.65 to $7.75 a share, up from a previous ceiling of $7.25. Even the lower end of the revised range exceeds the average analyst estimate tracked by Bloomberg. RTX also boosted its sales and free cash flow forecasts.
All three of RTX's main operating units reported double-digit organic sales growth in the quarter. Adjusted earnings topped $2.26 a share, beating expectations, though the figure included a 25-cent gain from recovering tariffs the Supreme Court struck down earlier this year.
Goldman Sachs aerospace and defense analyst Noah Poponak shared his initial view with clients: "Solid quarter and guidance raised."
More color from Poponak:
Bottom Line: RTX 3Q26 results came in ahead of consensus across key metrics, with revenue and segment EBIT ahead in all three segments. Collins EBIT includes +$250mn of IEEPA recovery, and Pratt EBIT includes +$160mn of IEEPA recovery. The company raised its 2026 guidance across the board, with organic revenue growth now at 10%-11% (vs. 8%-9% prior) and midpoint increases of 2% for revenue, 7% for EPS, and 6% for free cash flow, partially operational and partially IEEPA.