Last week, when we documented how Paramount's record bond offering cratered before the ink was dry, we flagged one line from the Bear Traps chat as deserving extra attention: "Paramount's existing unsecured bonds? Primed." Today, with the $110 billion Warner Bros. Discovery takeover officially closed and the combined company (now simply "Skydance", although "Skyfall" is certainly more appropriate) open for business, Fitch made it official.
In a rating action timed to the close, Fitch cut Paramount Skydance and WBD's issuer ratings deeper into junk territory, to BB from BB+, citing "materially higher leverage" and "significant execution and integration risks." But the real damage was further down the stack: Paramount's legacy senior unsecured notes were downgraded to BB- with a Recovery Rating of RR5, which in Fitch-speak means expected recovery of just 11% to 30% in a default. WBD's leftover unsecured notes fared worse still, cut to B+/RR6 (0% to 10%).
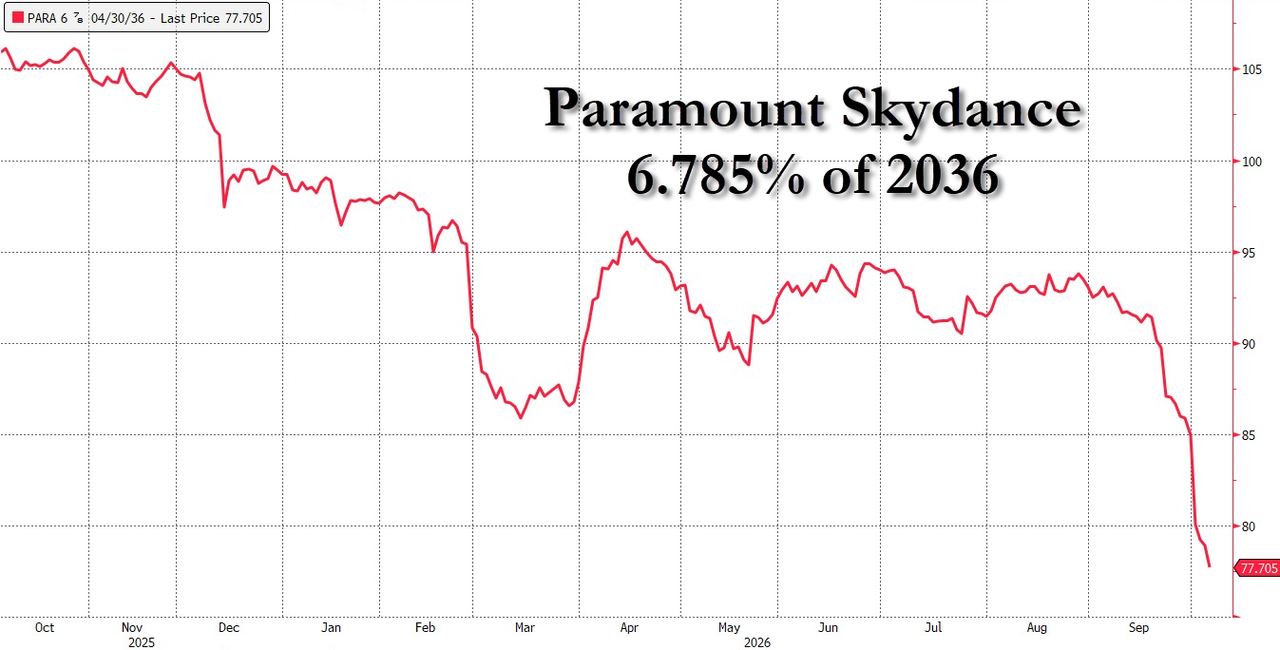
The market got the message. The old Paramount 6.875% notes due 2036 (originally Viacom paper) plunged to a record low of 77.7, down from 105 a year ago and roughly 92 as recently as mid-September. That's ~14 points in three weeks, and a yield of roughly 10.6% by our math, on a bond that was trading above par last fall.
Get In Line
The logic is simple enough. Before the d