By Benjamin Picton, Senior Market Strategist At Rabobank
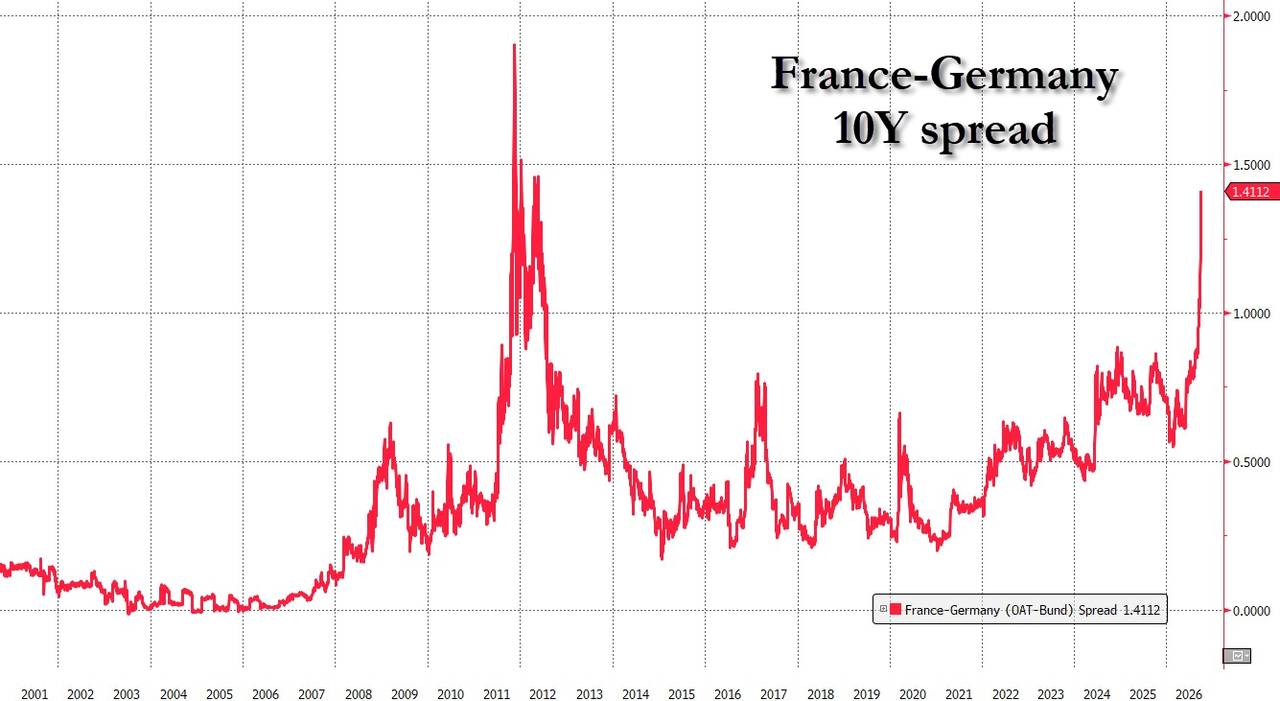
European equity indices fell sharply yesterday, pacing gains in sovereign yields for France, Italy and Greece. The spread between 10-year OATs and Bunds blew out to more than 140bps as the French government unveiled plans for €43bn worth of spending cuts and higher taxes in an effort to tackle France’s yawning fiscal deficit. The plan contains cuts to France’s social security system, including partial freezes to pensions indexation, trimming of retiree tax benefits, and a slower projected pace of healthcare spending growth.
Nevertheless, the market reaction suggests that investors are not optimistic about the prospects for reform. Firstly, the projected result is not exactly stellar. If all the measures are enacted the fiscal deficit would only fall from 5.4% to 5%. Secondly, social security retrenchment has proven an intractable challenge that has outlasted several governments and the prospects for successfully steering reform through a fractured national parliament a few months out from a contentious Presidential election where the leading candidates on the populist left and right generally oppose pension reform are not strong.
The sense that the French administrative state lacks the capacity to reform itself is reflected in the fact that the sovereign spread to bunds is now substantially worse than is the case for Italy and Greece. Those two were among the ‘PIIGS’ during the European sovereign debt crisis of the early 2010s and were previous viewed as the worst offenders in terms of fiscal responsibility. No longer.
The French government now says tha