Authored by Lance Roberts via RealInvestmentAdvice.com,
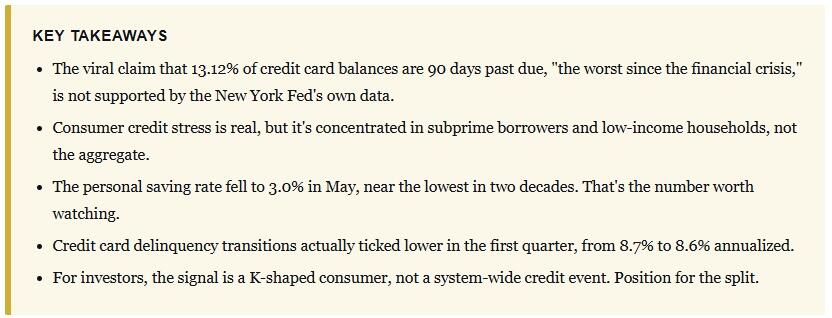
A viral stat claims credit card delinquencies just hit their worst level since 2008. However, the New York Fed’s own data shows the opposite, and the real consumer credit stress is hiding exactly where the headlines aren’t looking.
A number has been making the rounds all year, and it’s misleading. The claim: roughly 13% of credit card balances are 90 days or more past due, the worst since 2008. Here’s the twist. That number is real, and it comes straight from the New York Fed. It just doesn’t mean what the scary charts say it means.
Sorting the real signal from the viral one matters because one of them belongs in your portfolio decisions and the other belongs in the trash.
Where The Scary Number Comes From
Let’s start with the Q2 2026 Household Debt and Credit Report, released August 11. Total household debt actually fell $13 billion on the quarter, a rounding error of 0.1%, to $18.8 trillion. Credit card balances rose $21 billion to $1.26 trillion, up 1.7%. So far, nothing that looks like a crisis.
However, this is the point where you are hit with the delinquency rate that everyone screenshots. The share of card balances 90 days or more past due has climbed from 7.6% in late 2022 to 12.8%. That is a real figure from the Fed’s data, and it’s the source the viral posts were reaching for